Written by Jovan Johnson, Esq., Structured Settlement & Annuity Specialist
Industry-Reviewed by Kevin Lowe, COO of Genex Capital, Structured Settlement Secondary Market Specialist
Updated: July 19, 2026
Selling a structured settlement in New York means navigating the state’s Structured Settlement Protection Act and getting a judge’s sign-off before you can be paid. Here’s exactly what that process looks like, and what it takes to get there.
Can I Sell My Structured Settlement in New York?
Yes, you can sell a New York structured settlement, in full or in part. New York law (General Obligations Law § 5-1701 et seq.) requires: a written disclosure statement at least 10 days before you sign anything, a court petition filed in Supreme Court, at least 20 days’ notice before your hearing, and a judge’s finding that the sale is in your best interest. Most
sales close in 45–60 days from signed agreement to funded payment.
See What Your Payments Could Be Worth
Every offer is different, and the only way to know what your specific payments are worth is to get an actual quote — not a generic estimate.
AnnuityFreedom.net connects New York sellers with our funding partner’s team at no cost and no obligation to move forward. You’ll get a real quote based on your actual payment schedule, an explanation of the required disclosures before you sign anything, and guidance through the New York court approval process from people who handle these filings regularly. There’s no fee to get a quote, and requesting one doesn’t commit you to selling.
→ Request your free New York structured settlement quote
What is a Structured Settlement?
A structured settlement is a set of tax-free payments made on a regular schedule following a lawsuit settlement, typically funded through an annuity issued by an insurance company.
How to Sell a Structured Settlement in New York (Step by Step)?
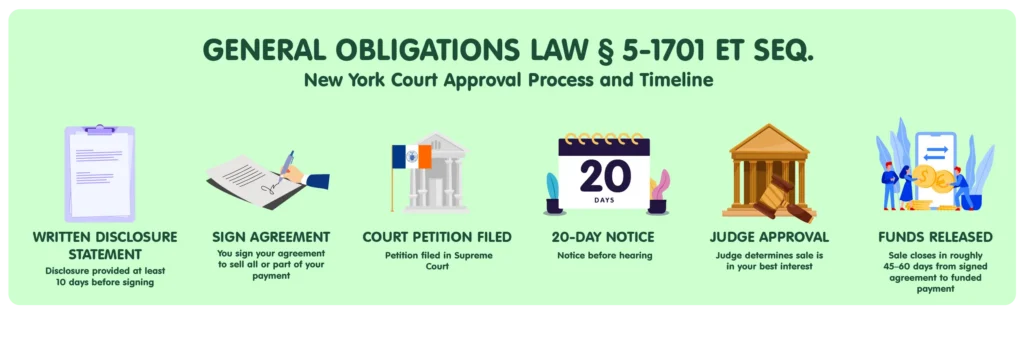
1. Get quotes from more than one factoring company
Industry-wide, discount rates on structured settlement purchases commonly run 9%–18%. Sellers who work with AnnuityFreedom.net’s network have accessed rates as low as 8% in qualifying cases — worth asking about when you compare quotes, since it isn’t guaranteed for every case but can meaningfully change your net proceeds.
2. Receive your written disclosure statement — at least 10 days before signing
Under General Obligations Law § 5-1703, the buyer must give you a disclosure statement at least ten days before you sign a transfer agreement. It has to spell out the payments being transferred, their total value, the discounted present value using a federally specified rate, and every fee being deducted.
3. Sign the transfer agreement
Once you’re satisfied with the offer and disclosures, you sign the agreement — but the sale isn’t final yet.
4. Your case is filed in New York State Supreme Court
This isn’t an ordinary lawsuit — it’s a special proceeding filed under General Obligations Law § 5-1705, brought in the Supreme Court of the county where you live (or, if you don’t live in New York, the county where your settlement was originally approved). That rule applies statewide: if you live in Buffalo, Rochester, Syracuse, Albany, on Long Island, or anywhere else in New York, your case is filed in your home county’s Supreme Court. If you live in New York City specifically, that means Supreme Court in your home borough — Kings (Brooklyn), Queens, New York (Manhattan), Bronx, or Richmond (Staten Island) County. You don’t need to hire your own litigation attorney to appear; the buyer’s counsel typically prepares and files the petition, and you’re notified of the hearing date and may attend.
5. You (and any dependents) get at least 20 days’ notice before the hearing
General Obligations Law § 5-1705(c) requires the petition and notice of hearing to be served on you at least twenty days before the scheduled court date.
6. A judge reviews the sale at a court hearing
The judge must find on the record that the sale is in your best interest, considering the price you’re getting, the fees involved, and your reasons for selling. Cases involving a minor’s structured settlement face the same court-approval requirement, and a parent or guardian must show the court there’s an urgent need for cash.
7. Funding — typically 45–60 days after you sign
Once the judge signs the approval order, the buyer funds your lump sum.
A Real Driver of Large New York Settlements: The Scaffold Law
New York Labor Law § 240, the “Scaffold Law,” imposes strict liability on property owners and contractors for gravity-related construction injuries — one reason New York produces an unusually high share of the large personal injury settlements that later get structured and, sometimes, sold.
If Something Goes Wrong: New York’s Consumer Protection Resources
- NY Department of Financial Services — dfs.ny.gov/complaint, (800) 342-3736, for complaints involving the annuity issuer.
- NY Unified Court System self-help resources — nycourts.gov/courthelp.
A Worked Example
Hypothetical only: a payee owed $1,000/month for 10 more years ($120,000 total) might see an offer in the rough range of $68,000–$74,000 in present-value terms at an 11% discount rate (within the industry-wide 9%–18% range — sellers who qualify for AnnuityFreedom.net’s network rate as low as 8% could see a somewhat higher net figure), before fees — subject to the same court review above.
New York Structured Settlement FAQ
How long does it take to sell a structured settlement in New York?
Typically 45–60 days, covering the 10-day disclosure period, the 20-day court notice period, and the hearing itself.
How much money will I get for my structured settlement?
It depends on the discount rate applied. Industry-wide, that’s commonly 9%–18%, though sellers who qualify through AnnuityFreedom.net’s network have accessed rates as low as 8% — plus how many payments you’re selling and how far in the future they’re scheduled. Selling sooner-due payments generally nets you more per dollar of face value than payments decades out.
Can I sell only part of my structured settlement?
Yes — New York law allows partial transfers, so you can sell a portion of your payment rights and keep the rest on the original schedule. The same court approval process applies either way.
Which court handles my case?
The Supreme Court in your home county — everywhere in New York State, not just New York City. If you live in one of the five boroughs, that’s Kings, Queens, New York, Bronx, or Richmond County specifically; anywhere else in the state, it’s your own county’s Supreme Court. See General Obligations Law § 5-1705.
Do I need my own lawyer to sell?
No — New York requires that you be notified of your right to independent professional advice, but doesn’t require you to retain one to complete a sale.
Ready to Get a Real Number?
Now that you know how the process works, the next step is seeing what it means for your specific payments. Get a free, no-obligation quote and walk through the New York court process with people who handle these filings regularly.
Sources
About the Author
Jovan Johnson, Esq. is a structured settlement & annuity specialist with 12 years of experience, based in California. He has also practiced as an attorney in consumer and small business bankruptcy and debt settlement. Annuity Freedom has been helping clients sell annuity payments since 2017.
About the Reviewer
Kevin Lowe is the Chief Operating Officer of Genex Capital and has more than a decade of experience in specialty finance and the structured settlement secondary market. Since joining Genex in 2013, he has overseen transaction management, investor relations, compliance, and strategic initiatives across the United States, working closely with annuitants, investors, legal professionals, and financial institutions.
Disclaimer
This article is for informational purposes only and isn’t a substitute for independent professional advice.